
The 2026 edition of “ZeroedIn: The Brand Marketing Pulse” is now live.
California’s 2026 Climate Reporting Resources and Platform Are Live: What to do by 10 November
On 1 September 2026 the California Air Resources Board (CARB) published a set of resources to help companies prepare and submit their first Scope 1 and Scope 2 emissions reports under SB 253. If your business is in scope, the work now has a fixed end date: 10 November 2026.
SB 253 (Health and Safety Code section 38532) covers US-based companies with total annual revenues above $1 billion that do business in California. This first year covers Scope 1 and Scope 2 emissions for your prior fiscal year. Scope 3 joins the requirement from 2027.

CARB has built a 2026 Report Intake Platform, and using it is entirely optional. It does two things. It gives you a place to send CARB your contact details ahead of the deadline, which helps CARB administer the new reporting fee. It also provides fields to submit your Scope 1 and Scope 2 emissions directly, if you would rather do that than prepare a separate submission.
You can open the platform here: 2026 Report Intake Platform.
If you prefer to keep things simple, you can still email your emissions report and contact details to climatedisclosure@arb.ca.gov. CARB has recorded a video walk-through of the platform, and has published a ‘Guidance Document for SB 253 2026 Reporting Submittals’ covering how submissions should be put together.
The Board approved the Initial Regulation on 26 February 2026. It sets the first-year reporting deadline and introduces the fee component under section 38532. One detail worth tracking: the regulation only takes effect once the Office of Administrative Law approves it, at Title 17 of the California Code of Regulations, Article 6, sections 96070 to 96077. Both the 10 November deadline and the reporting duty itself sit inside that regulation, so it’s worth following the OAL step rather than treating the text as settled.
If you’re already reporting under CSRD, SECR, CDP or ISSB (IFRS S2), most of the underlying data exists somewhere in your organisation. The work is usually reconciliation and evidence rather than starting again.
SB 253 reports should cover your company’s fiscal-year data. For the first reporting cycle (due 10 November 2026), CARB has set two tracks to ensure every entity has at least six months to prepare:
If you are unsure which fiscal year applies, get in touch with us at info@51tocarbonzero.com and we can help you figure it out.
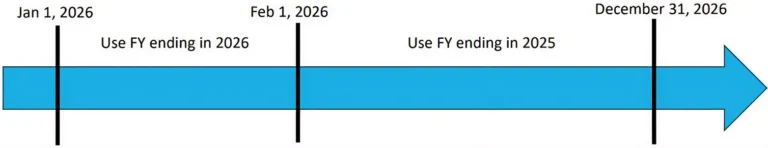
CARB SB 253 reporting year scheme.
We provide Scope 1 and Scope 2 measurement, boundary setting and disclosure submissions across all sectors, and we have a 100% audit pass rate across our client base. Every client works with a named Climate Success Manager under our Climate Unlimited™ model, so the advisory support sits alongside the data rather than being bought in separately. Our platform provides fully trail data to make life easy at audit time.
If you’d like a view on whether SB 253 catches your business, or help getting a submission ready before 10 November, get in touch at info@51tocarbonzero.com or 020 4578 4040.